World ID Brings Human Verification Into The Banking Fraud Debate
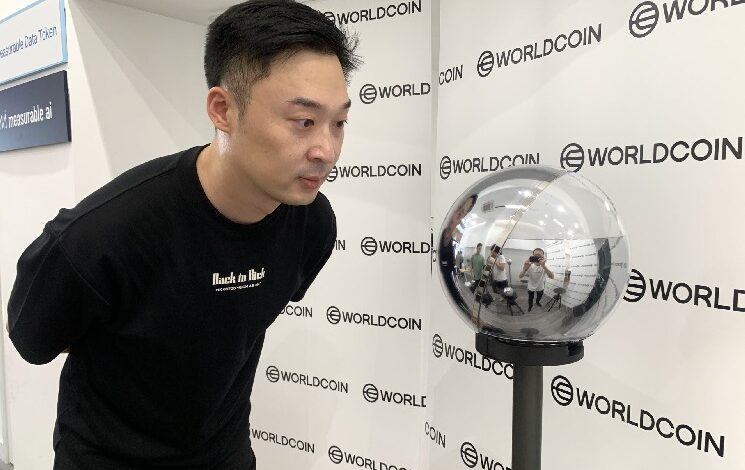
World launched its banking-and-finance providing on October 18. For a financial institution contemplating human verification, the helpful query is narrower than whether or not an interplay seems genuine: what precisely does the proof set up, and what should the establishment nonetheless confirm?
- Human uniqueness, current participation and doc attributes reply completely different questions.
- Identification proof doesn’t set up permission for each monetary motion.
- Restoration, privateness and transaction authorization stay a part of the entire management system.
A human sign isn’t a whole cost approval
The launch assertion addresses monetary establishments and AI-agent interactions. In both setting, the worth of a credential relies on matching the very fact it proves to the choice being made.
World’s technical overview distinguishes three credentials. Proof of Human considerations uniqueness by means of Orb verification. Proof of Presence makes use of a selfie-based test. Proof of Attributes considerations possession of a supported authorities doc. These mechanisms shouldn’t be handled as interchangeable assurances.
A novel particular person can nonetheless be an unauthorized particular person. A real worker could lack authority to approve a big switch, and a certified buyer could also be deceived about its recipient. Passing a human-verification test can’t resolve the transaction’s total business context.
The broader authentication distinction can also be mirrored in NIST’s digital-identity steerage, which treats a biometric attribute as inadequate by itself for the authentication combos it specifies. That’s an impartial framework reference, not a press release that World has or has not met a specific certification.
Transaction-risk screening consequently stays a separate layer. Establishing a truth a few participant and evaluating the vacation spot of a cost are complementary duties.
Brokers make the bounds of delegation extra vital
For a hypothetical assistant paying an bill, proving that an actual buyer stands behind the request could be helpful. The service would nonetheless have to know which account the assistant could use, the spending restrict, the permitted recipient and when its authority expires.
That permission additionally wants a revocation path. A buyer who loses a tool or modifications their thoughts should have the ability to withdraw authority with out counting on the agent to cooperate. A document of earlier consent can’t turn into limitless permission for future transfers.
The operational problem resembles the controls thought of in pockets financial-crime steerage. Understanding the connection behind a switch takes greater than recognizing an handle or accepting a single credential.
Privateness wants the identical precision. A proof could cut back the information shared in a single verification step whereas the encompassing service nonetheless collects transaction information and account data. The entire information circulate issues to the shopper.
As AI-facing monetary purposes develop, the strongest implementations will clarify the boundary clearly: which truth is confirmed, which permission has been granted and what extra checks govern the motion of cash.
Written by the Information Desk and edited by Samuel Rae.