IMF finds most tokenized stock trades involve less than one share
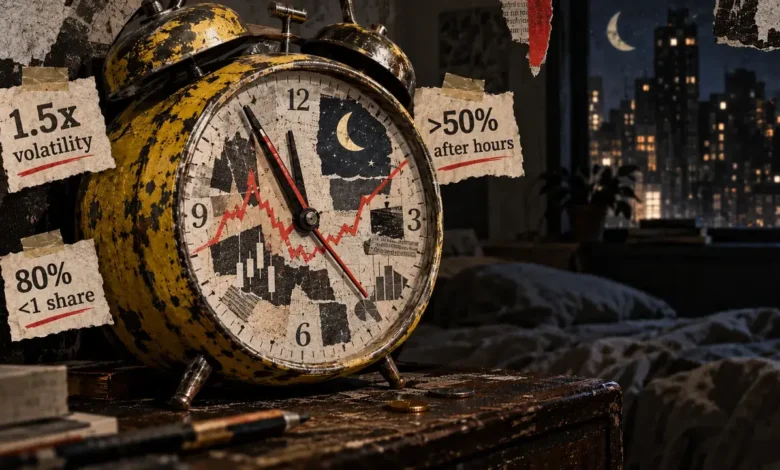
Greater than half of sampled tokenized US inventory buying and selling happens outdoors Wall Avenue’s common hours, the Worldwide Financial Fund (IMF) discovered.
The IMF’s October Global Financial Stability Report additionally confirmed that roughly 80% of tokenized fairness transactions concerned lower than one share, offering proof of demand for fractional investments and around-the-clock entry to American securities.
Nevertheless, the examine discovered that tokenized equities skilled roughly 50% greater realized volatility than their conventional counterparts, whereas fragmented buying and selling venues supplied considerably weaker liquidity.
The findings come as exchanges and monetary establishments increase efforts to convey US equities onto blockchain infrastructure, doubtlessly difficult standard market hours and settlement preparations.
Tokenized inventory costs replicate in a single day market exercise
The IMF examined 5 of essentially the most actively traded tokenized US fairness merchandise issued by Ondo and xStocks, overlaying publicity to the S&P 500, Nasdaq, Tesla, Alphabet and Nvidia.
The evaluation lined 11 centralized and decentralized buying and selling venues, with greater than 2 million five-minute worth and trading-volume observations collected over 365 buying and selling days.
The sampled merchandise represented roughly $345 million in market worth, or 15% of the $2.3 billion tokenized fairness market as of July 31.
The buying and selling patterns confirmed that buyers have been actively utilizing options unavailable throughout standard US stock-market classes.
Greater than half of buying and selling quantity occurred outdoors the common 9:30 a.m. to 4 p.m. Japanese session, together with in a single day and weekend durations.
The IMF stated the exercise advised demand from buyers working in several time zones and people searching for to answer market developments with out ready for American exchanges to reopen.
The predominance of transactions smaller than one share additionally pointed towards a retail-oriented market, though the researchers inferred that participation from commerce sizes slightly than immediately figuring out particular person buyers.
Extra considerably, the examine discovered that in a single day tokenized-stock costs contained info subsequently mirrored in standard fairness markets.
Utilizing centralized-exchange knowledge, IMF researchers in contrast in a single day tokenized worth actions with the efficiency of their underlying securities in the course of the first 5 minutes of the following US buying and selling session.
The estimated pass-through ranged from 87% to 99%, indicating a powerful relationship between in a single day tokenized returns and subsequent worth changes in conventional markets.
The findings counsel that tokenized venues can replicate info whereas standard exchanges are closed, though the evaluation doesn’t set up that on-chain buying and selling causes the corresponding worth actions.
Each markets could also be responding to the identical developments, with standard shares adjusting quickly as soon as buying and selling resumes.
Greater volatility threatens tokenized shares’ growth
The rising exercise outdoors Wall Avenue’s working hours comes with vital variations in market high quality.
The IMF discovered that conventional exchanges remained considerably extra liquid than tokenized buying and selling platforms, with centralized crypto venues performing higher than decentralized exchanges.
On decentralized platforms, comparatively small transactions may produce disproportionately giant worth actions due to restricted market depth and market-making exercise.
Realized volatility throughout tokenized equities was about 1.5 occasions that of their conventional equivalents and rose additional on decentralized venues.
The comparability partly displays totally different buying and selling home windows, since tokenized merchandise commerce repeatedly whereas the traditional-market measure covers common US hours.
Regardless of these variations, tokenized costs usually tracked their underlying securities throughout common buying and selling classes. Nevertheless, decentralized venues noticed wider and extra frequent worth deviations, particularly when buying and selling volumes have been low.
These situations may complicate growth past the comparatively small market presently served by tokenized equities.
The IMF estimated that public tokenized real-world property, excluding repurchase agreements and stablecoins, had reached roughly $65 billion by July, in contrast with roughly $300 trillion in conventional capital-market property.
The Fund stated systemic dangers stay restricted at present adoption ranges, however broader use of steady buying and selling and automatic settlement may speed up market stress.
Automated collateral administration, for instance, may set off margin calls and compelled liquidations outdoors standard buying and selling hours, doubtlessly amplifying promoting strain when obtainable liquidity is already skinny.
The IMF recognized authorized certainty, regulatory readability, interoperability between buying and selling networks and dependable settlement property as main constraints on additional progress.
Questions additionally stay over the rights hooked up to tokenized securities, significantly whether or not holders obtain direct possession claims over underlying shares or contractual publicity to their costs.
To handle the rising dangers, the IMF referred to as for circuit breakers, buying and selling halts and liquidity safeguards tailored to steady markets, alongside stronger monitoring of connections between tokenized and conventional finance.
Regulators should additionally assess whether or not present protections can function throughout weekends and in a single day buying and selling, when automated liquidations could happen with out the liquidity usually obtainable throughout Wall Avenue’s common session.