Bitcoin hedge funds can get liquidated even when their trades are profitable
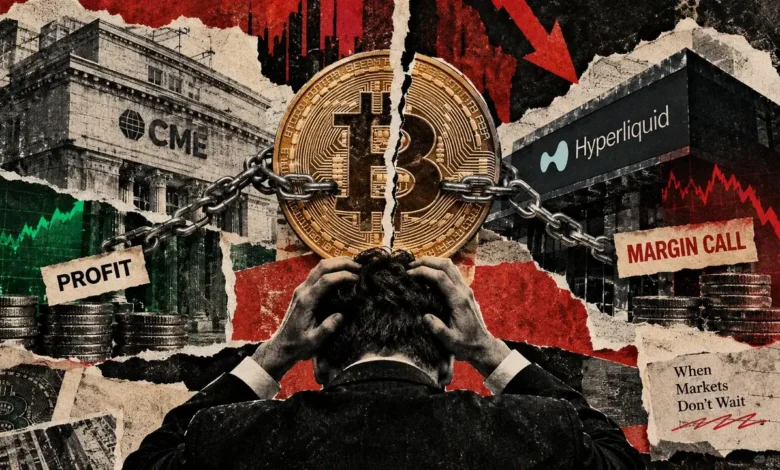
Here is a hypothetical state of affairs: a hedge fund is earning profits, however one in all its exchanges is about to liquidate its place anyway. Bitcoin has fallen, its brief place on CME is worthwhile, and the matching lengthy on Hyperliquid is bleeding money. The 2 trades have been designed to offset one another, however Hyperliquid cannot use earnings sitting at CME to cowl the losses by itself books. The fund has to seek out extra collateral earlier than the alternate closes the place for it.
Transferring cash between exchanges takes time, and through a downturn, withdrawals can decelerate or cease altogether. The fund may have the funds for to cowl each place and nonetheless lose half its hedge as a result of the earnings are sitting in numerous accounts.
As soon as that occurs, a method designed to keep away from betting on Bitcoin’s route can immediately turn out to be a really giant wager on the place the worth goes subsequent.
Within the high-stakes world of institutional Bitcoin buying and selling, a fund will be worthwhile throughout its total portfolio and nonetheless face pressured liquidation as a result of the alternate holding its shedding place does not know or care in regards to the cash it has made someplace else.
And the extra effectively the fund makes use of its capital, the much less cash it could have sitting round to unravel the issue.
A 20% Bitcoin crash can break a wonderfully good hedge
Here is one other hypothetical state of affairs: a fund holding two opposing Bitcoin positions. It is lengthy Bitcoin on Hyperliquid and brief Bitcoin futures on CME, with each positions price $4.5 million.
If Bitcoin falls 20%, the brief place earns roughly $900,000 whereas the lengthy loses roughly the identical quantity, assuming each contracts observe the worth equally. On paper, the fund hasn’t misplaced a lot from Bitcoin’s directional transfer. Its brief has offset its lengthy, which was the complete level of the commerce.
However sadly, the exchanges do not see it that manner.
Hyperliquid sees a shedding place and demands enough collateral to maintain it open. CME sees a worthwhile brief place, however these earnings are in a special account, topic to completely different margin and settlement preparations. The fund must switch a few of these earnings or shut each positions earlier than Hyperliquid decides to liquidate the shedding one. If withdrawals are delayed, transfers are frozen, or the worthwhile commerce cannot be closed shortly sufficient, the fund can discover itself in need of cash in a single account regardless of having sufficient property throughout the portfolio.
As soon as Hyperliquid liquidates the lengthy, the fund is left holding a brief place that not has an offsetting commerce. Now it loses cash if Bitcoin rebounds, having gone to appreciable hassle to keep away from betting on Bitcoin’s route within the first place.
Ian Weisberger, CEO of buying and selling expertise supplier CoinRoutes, pointed to the disorderly alternate liquidations throughout the October 2025 crypto crash for instance of how harmful this could turn out to be. Merchants who thought their portfolios have been balanced may immediately be left uncovered as a result of a person alternate closed one place with out accounting for the opposite.
The issue is not essentially that the fund made a foul wager; it is that the cash wanted to maintain the wager alive was sitting someplace the alternate could not attain.
A million {dollars} goes a (surprisingly) great distance
The issue turns into extra difficult when funds use borrowing and derivatives to stretch comparatively small quantities of capital into a lot bigger positions. Weisberger defined to CryptoSlate how a hedge fund depositing $1 million in USDC may, in idea, find yourself controlling $9 million price of Bitcoin positions.
The fund begins with $1 million of its personal capital and borrows one other $2 million from a lender, giving it $3 million to work with. It allocates $1.5 million to CME and $1.5 million to Hyperliquid, then makes use of derivatives to determine a $4.5 million place on every alternate. It may well purchase $4.5 million price of Bitcoin publicity on Hyperliquid whereas promoting $4.5 million by means of CME futures. That is $9 million in complete positions, financed with $1 million of the fund’s personal cash, $2 million borrowed from a lender, and extra leverage by means of derivatives.
The fund is not essentially betting that Bitcoin will go up or down. If Bitcoin goes up 10%, the lengthy makes roughly $450,000 whereas the brief loses about the identical quantity, assuming each contracts observe the worth equally. As an alternative, the fund desires to gather the distinction between futures costs, perpetual funding funds, or different small discrepancies, with its opposing positions retaining many of the directional publicity out of the commerce.
The issue is that the hedge nonetheless has to work in observe.
Any one in all 100 various things may go mistaken: futures and perps can transfer aside, funding funds can turn out to be costly, and even a 1% discrepancy between two $4.5 million positions quantities to a $45,000 distinction. Even when the costs finally converge, the fund wants sufficient collateral to outlive no matter occurs in between. And though the positions are presupposed to offset one another, the exchanges nonetheless make their very own margin selections.
CME will not waive a collateral requirement as a result of the fund has a worthwhile place on Hyperliquid, and Hyperliquid will not routinely credit score earnings that have not been transferred from CME. Conserving giant deposits at each exchanges will surely assist, however that may get costly fairly quick when the complete enterprise depends upon making small quantities of cash from variations between markets.
The choice is to make the identical capital work more durable, which introduces one other downside: the extra publicity a fund can help with each greenback, the extra dependent it turns into on having the ability to entry that greenback when one thing goes mistaken.
The alternate does not care that your different commerce is worthwhile
Conventional prime brokers have spent a long time serving to hedge funds handle financing, collateral, and buying and selling throughout completely different markets, however crypto markets have at all times been rather more fragmented.
Funds buying and selling Bitcoin futures at CME, perpetual contracts at Hyperliquid, and spot Bitcoin on one other alternate want to take care of separate swimming pools of collateral even when all of these positions are primarily a part of the identical technique. It’s because each alternate has its personal margin necessities and settlement processes.
CRX Commerce, a Swiss institutional prime brokerage constructed on CoinRoutes expertise, is now making an attempt to coordinate these preparations. It permits skilled merchants to handle Bitcoin, stablecoins, and tokenized property as collateral throughout crypto exchanges and conventional markets, together with Hyperliquid and CME. As an alternative of funding every alternate individually and hoping cash can transfer shortly sufficient when one thing goes mistaken, funds can handle their positions and financing by means of one account.
Weisberger stated the system considers each the full measurement of a fund’s positions and the way a lot directional danger stays once they’re assessed collectively. That is additionally why a lender may comply with finance a fund controlling 9 occasions its unique capital in buying and selling publicity. The shopper has borrowed $2 million relatively than $9 million, and the lengthy and brief positions are presupposed to offset one another.
CRX’s danger engine displays positions throughout the portfolio and may start lowering publicity earlier than a person alternate forces a liquidation. Beneath one strategy, known as delta-neutral liquidation, it makes an attempt to shut each side of a hedge collectively. If a fund is brief a Tesla perpetual and lengthy an equal quantity of tokenized Tesla shares, the system can unwind each positions as a pair as an alternative of leaving the shopper with an undesirable wager on Tesla. One other methodology reduces whichever place contributes essentially the most directional danger.
Each approaches are designed to keep away from the state of affairs the place an alternate closes the shedding half of a commerce and leaves the fund uncovered to a market transfer it was making an attempt to hedge.
However there is a restrict to what coordinated danger administration can accomplish. Software program cannot power an alternate to course of an order throughout an outage, and it could’t assure there will probably be somebody keen to take the opposite facet at an affordable worth. That is why the fund can nonetheless lose cash closing its positions, particularly when markets are shifting shortly and consumers disappear. And the exchanges nonetheless retain the proper to liquidate positions that fail to fulfill their margin necessities.
CRX can acknowledge that two positions have been meant to work collectively and attempt to hold them from being separated.
Bitcoin can finance trades even the place it is not accepted as collateral
The identical strategy may permit funds to make use of Bitcoin holdings to help trades in markets the place Bitcoin itself is not accepted as collateral.
Weisberger defined this utilizing an instance of a shopper holding $1 million in Bitcoin that wishes to commerce CME futures. The shopper transfers the Bitcoin to a crypto alternate, sells $500,000 price, and replaces that portion of its holdings with $500,000 in Bitcoin futures or perpetuals. The fund now owns $500,000 in Bitcoin and has one other $500,000 in spinoff publicity, so its sensitivity to Bitcoin’s worth is roughly the identical. The spot sale has freed up $500,000 in money, which might transfer by means of CRX’s USDC infrastructure to help buying and selling at CME.
The cash is not getting used twice right here. Solely half the unique Bitcoin has been offered, and the fund has purchased a contract to interchange the publicity it gave up. That contract has its personal margin necessities and financing prices, and the place will be liquidated if the fund cannot hold sufficient collateral behind it.
Weisberger estimated that borrowing money instantly in opposition to Bitcoin would sometimes value round 8%, whereas changing some spot publicity with derivatives means paying the related futures foundation or perpetual funding price as an alternative. That may very well be cheaper, though funding funds can fluctuate, and the fund nonetheless has to account for charges and spreads.
The corporate did not present a full comparability of precise prices beneath each preparations. In both case, the fund discovered a strategy to put extra of its present capital to work. It additionally added one other place that wants financing, margin, and somebody keen to maintain the commerce open when markets turn out to be disorderly.
Conserving collateral away from exchanges does not remove the danger
One strategy to cut back publicity to an alternate failure is to keep away from retaining all of the collateral on the alternate within the first place. CRX makes use of tri-party settlement the place obtainable, retaining collateral with a separate custodian as an alternative of depositing it instantly on the buying and selling venue. The alternate processes the trades, however the property stick with the custodian, and revenue and loss is settled periodically.
Weisberger stated these settlements can happen each eight or 24 hours. This will restrict the quantity instantly uncovered to an alternate withdrawal freeze to the unsettled revenue and loss relatively than the shopper’s total collateral deposit. However the extent of that safety depends upon the agreements and settlement preparations, and it does not stop an alternate outage from interfering with trades that have to be closed.
It additionally introduces one other establishment whose obligations matter when one thing goes mistaken. CRX Commerce is operated by RAS Capital, a Swiss monetary middleman affiliated with VQF, a regulator-recognized self-regulatory group. It is not a financial institution or securities agency and does not present loans itself. Financing comes from impartial lenders utilizing the platform. Weisberger stated purchasers retain authorized possession of property held in devoted, segregated wallets and alternate subaccounts.
Nevertheless, if a shopper borrows cash, the lender receives a lien over the portfolio collateral beneath a separate settlement. The Bitcoin nonetheless belongs to the shopper, however the lender has a legally enforceable declare in opposition to the pledged collateral if the shopper fails to fulfill its obligations. The settlement determines how a lot the fund can borrow, how the property are valued, and when the lender can train its rights.
In the meantime, the exchanges have their very own margin necessities and contracts with the dealer, whereas the custodian operates beneath one other settlement governing the place property are held and who can entry them.
Bringing every thing into one account does not remove any of these relationships, simply makes them simpler to coordinate.
CRX did not present the custody and lending agreements wanted to determine precisely what would occur if the platform, a custodian, or one in all its lending companions turned bancrupt. Weisberger stated purchasers retained possession by means of segregated wallets, however recovering property in an insolvency would rely upon the contracts and legal guidelines governing every relationship.
One other necessary query is whether or not collateral will be pledged onward, one thing the corporate’s responses did not set up. So whereas retaining collateral away from an alternate can cut back one kind of danger, it does not essentially imply the property will probably be instantly obtainable when one other establishment calls for cost.
Everybody nonetheless desires their a refund
There’s one other downside with constructing giant positions on borrowed capital, which is that, finally, the lender will need its a refund.
Weisberger stated loans organized by means of CRX often run for 30 to 90 days, with leverage limits, collateral weights, and loan-to-value necessities agreed when the shopper borrows. The lender can decline to resume the mortgage when it matures, leaving the fund to repay the cash or discover another person keen to finance its positions. That may occur no matter whether or not the fund’s buying and selling technique is worthwhile.
Trade margin necessities and spinoff funding prices may transfer throughout the mortgage time period, no matter what the lender initially agreed to. So funds can then face calls for for extra collateral from an alternate whereas additionally needing to repay or refinance cash borrowed in opposition to the identical portfolio. Shared collateral could make that portfolio extra capital-efficient, however it could’t override the lender’s contract or an alternate’s guidelines. And through a market disruption, the fund may have money at a number of exchanges directly, exactly when transfers turn out to be more durable and shutting positions will get costlier.
That is the trade-off behind making institutional Bitcoin buying and selling extra environment friendly. There is no cause for a fund to maintain unnecessarily giant quantities of capital scattered throughout exchanges if it could coordinate its positions and collateral extra successfully. Doing so can cut back pointless liquidations, release capital, and make hedged methods cheaper to function.
Nevertheless, it additionally permits funds to help bigger positions with out committing extra of their very own cash. And the bigger these positions turn out to be, the extra necessary it’s that lenders, exchanges, and custodians all do what they’re presupposed to do on the identical time.
The higher a fund will get at placing each greenback to work, the much less cash it has sitting round for emergencies. Shared collateral can cut back the danger of a worthwhile hedge being liquidated as a result of its cash is trapped within the mistaken account. It may well’t remove the underlying dependence on financing, liquidity, and alternate entry.
The actual measure of that effectivity will not be how a lot publicity $1 million can help when markets are calm, however how a lot of it the fund can safely hold open when everybody desires their a refund.