Standard Chartered says Ethena’s ENA can reach $2 by 2028
Normal Chartered expects Ethena’s ENA token to rise about sevenfold by 2028, offered the protocol can rebuild its shrinking synthetic-dollar enterprise.
The financial institution initiated protection of ENA with a $2 year-end 2028 goal, up from about $0.28 at the moment. It forecasts the token reaching $0.42 on the finish of 2026 and $1.10 in 2027 earlier than accelerating additional the next yr.
The projection would depart ENA outperforming Normal Chartered’s anticipated good points for each Bitcoin and Ethereum over the identical interval. However reaching it requires Ethena to reverse a contraction that has minimize USDe provide by greater than half from its peak and broaden far past the size it has beforehand achieved.
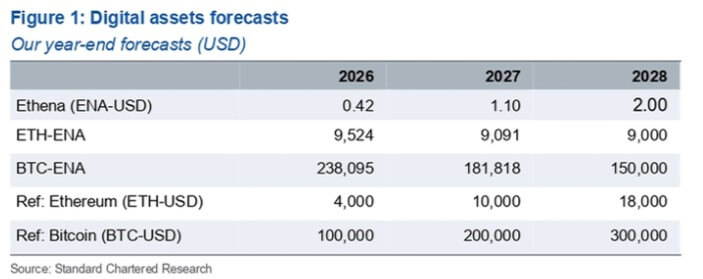
The financial institution’s thesis rests on Ethena discovering new sources of yield as returns from its unique crypto buying and selling technique decline, whereas producing sufficient income from a a lot bigger USDe base to make ENA more and more priceless to holders.
Ethena first has to rebuild USDe
USDe turned one among crypto’s fastest-growing stablecoins after launching in late 2023, exceeding $10 billion as merchants piled right into a construction that mixed lengthy spot crypto positions with quick perpetual futures.
That method allowed Ethena to seize funding funds whereas maintaining its general market publicity largely delta-neutral. At occasions, the technique generated returns above 20%, serving to appeal to deposits into USDe and its yield-bearing counterpart, sUSDe.
Nevertheless, these circumstances have since weakened amid the following market contraction.
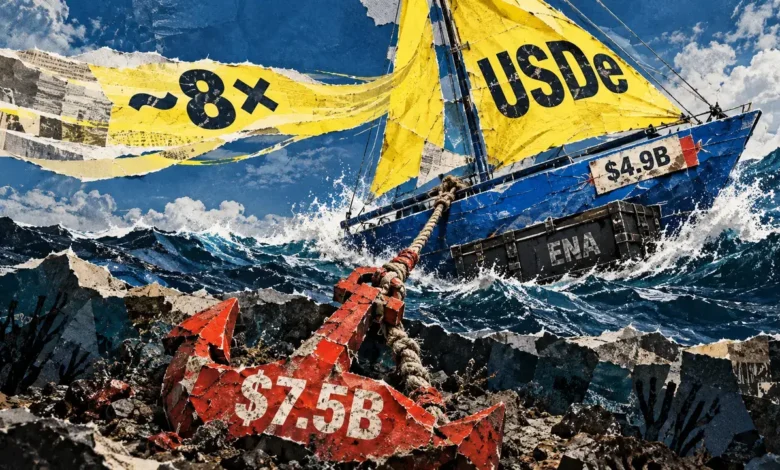
Because the commerce turned extra crowded and crypto funding charges compressed, USDe provide fell to about $4.9 billion. Normal Chartered estimates Ethena’s blended yield throughout its methods is now about 5.2%.
The financial institution’s forecast assumes contraction can reverse dramatically. It expects USDe provide to succeed in $40 billion by 2028, which means Ethena would first need to regain its earlier $10 billion-plus peak after which roughly quadruple once more.
Ethena has responded to decrease crypto foundation returns by broadening the place it generates yield. Its methods now embrace DeFi lending, institutional lending, liquid stablecoins and real-world belongings, alongside newer foundation trades tied to equities and commodities.
That diversification is central to Normal Chartered’s development assumptions.
The financial institution expects tokenized belongings, together with stablecoins and different real-world belongings, to succeed in about $4 trillion by the top of 2028 from roughly $350 billion at the moment. It tasks real-world belongings deployed on blockchains may rise from about $40 billion to $2 trillion over the identical interval.
A bigger tokenized-asset market would give Ethena extra collateral and yield alternatives past crypto derivatives, probably permitting USDe to broaden with out requiring one other interval of exceptionally excessive perpetual-futures funding charges.
Ethena can be constructing companies outdoors the core artificial greenback, together with white-label stablecoins and Ethena Pay. Normal Chartered expects these operations to widen the income base because the protocol grows.
Nevertheless, the primary hurdle is way nearer than $40 billion.
Ethena’s authorized fee-switch framework begins at $7.5 billion of USDe provide, leaving the protocol beneath the primary threshold at which the income mechanism underlying Normal Chartered’s valuation begins to take impact.
Why the buyback math results in $2
As soon as these thresholds are crossed, the ENA valuation more and more relies on how a lot of Ethena’s economics may be directed towards token holders.
The authorized framework allocates 95% of qualifying web income paid to the Ethena Basis from coated companies towards ENA buybacks. Ethena doesn’t retain the complete yield generated by the belongings supporting USDe, making the excellence between gross and web income central to the calculation.
Blockworks Advisory’s analysis modeled the protocol’s share of gross income rising with USDe provide, starting at about 5% round $7.5 billion and reaching 20% by $20 billion. The mannequin used a 6% protocol yield as an illustrative assumption, not a assured return.
On the a lot bigger scale envisioned by Normal Chartered, these economics turn out to be substantial.
The financial institution estimates that if USDe reaches $40 billion, ENA purchases may quantity to roughly 23% of the token’s present market worth yearly if its worth remained unchanged.
Normal Chartered doesn’t count on such a share to persist. It argues that buyers would capitalize the anticipated stream of purchases into ENA’s valuation, pushing the token larger and lowering annual buybacks as a share of its market capitalization.
The financial institution factors to Uniswap as an analog, saying UNI’s annualized buyback share has settled round 3% to 4% because the token appreciated after activating its charge change. Making use of a comparable equilibrium to Ethena underpins Normal Chartered’s $2 goal.
However the mechanism introduces its personal constraint.
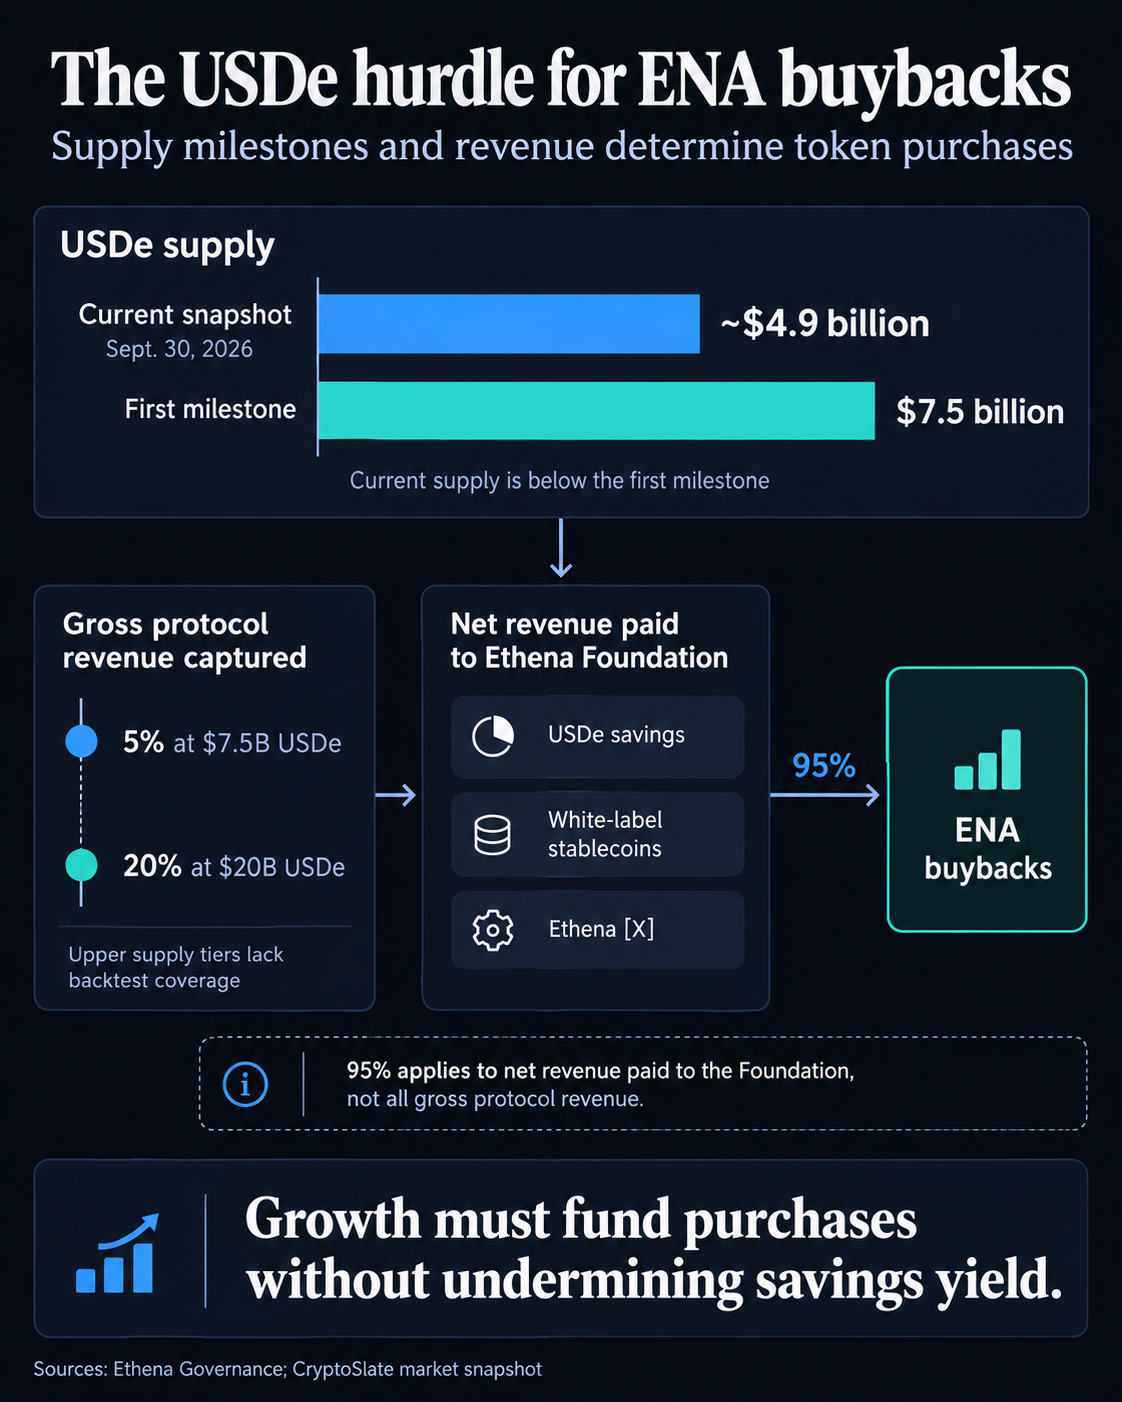
Capturing a bigger share of Ethena’s income for the protocol can scale back what stays out there to sUSDe holders. That creates a balancing act: Ethena wants sufficient margin to assist ENA purchases whereas sustaining sufficiently aggressive yields to maintain attracting the deposits required for USDe to develop.
The assumptions turn out to be extra demanding as provide rises. The 6% return used within the framework has not been assured throughout market cycles, whereas the upper revenue-capture tiers have but to be examined on the scale Normal Chartered expects.
That leaves buyers with a number of nearer-term checkpoints earlier than the $2 goal turns into related. USDe should first cross the $7.5 billion fee-switch threshold and reclaim its earlier peak.
Past that, Ethena should present that its newer yield methods can take in tens of billions of {dollars} with out materially compressing returns. How rapidly these thresholds are crossed will decide whether or not Normal Chartered’s projected buyback engine begins to resemble the one embedded in its valuation mannequin.