PropAMMs lower Solana trade costs, and public pool returns crash
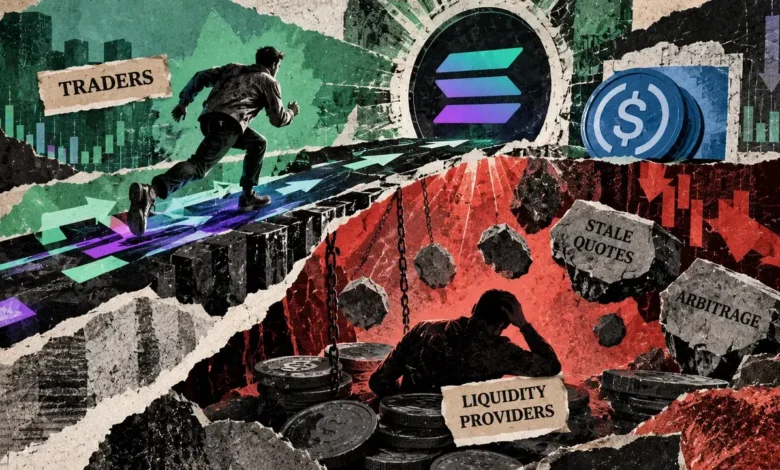
A dealer can get a greater Solana (SOL) swap worth whereas a passive pool depositor stays uncovered to merchants choosing off stale quotes, and a Sept. 29 preprint measures that divide.
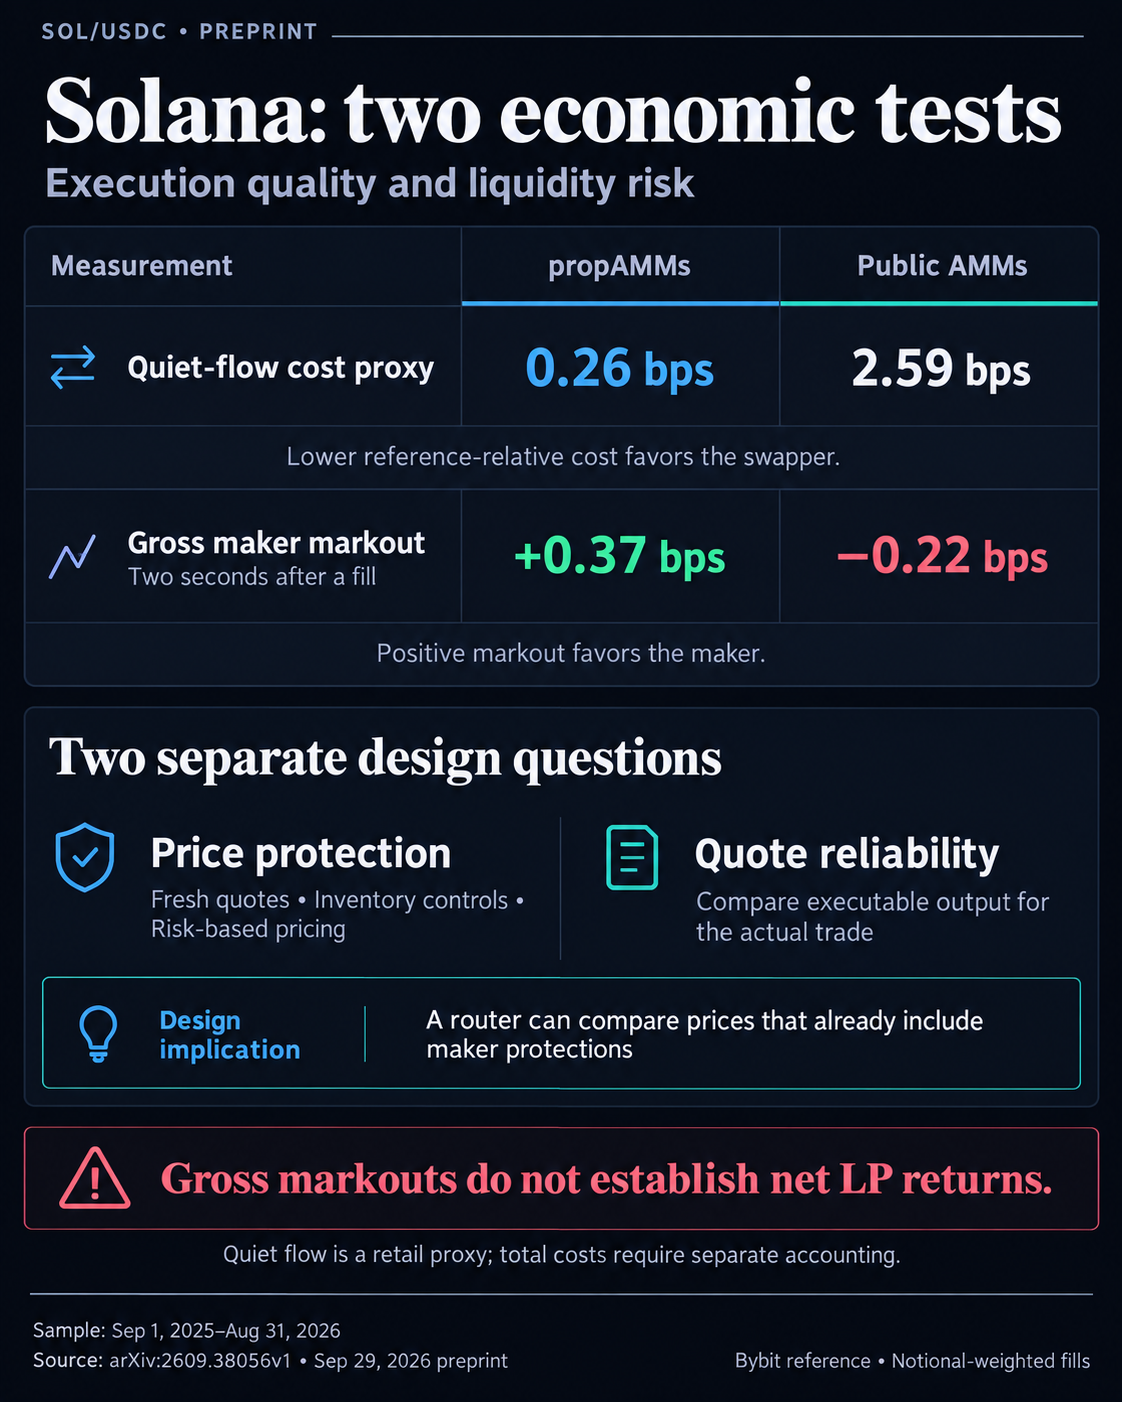
For quiet-market SOL/USDC fills, propAMMs, swimming pools managed by skilled operators, had a reference-relative execution price proxy of 0.26 foundation factors versus 2.59 for public automated market makers (AMMs).
The study covers Sept. 1, 2025, by way of Aug. 31, 2026, with shorter Base and Monad samples. It weights fills by notional in opposition to Bybit’s size-weighted top-of-book USDT microprice, transformed with its USDC/USDT midpoint. Its authors listing ETH Zurich and Class Labs affiliations.
A swapper needs extra tokens for a similar enter, whereas a depositor provides the stock others commerce in opposition to and wishes compensation for the dangers that stock carries. Low execution price can appeal to the primary participant with out being a adequate funding case for the second.
Swap costs and depositor returns on Solana
Throughout its Solana pattern, the paper reviews two-second gross maker markouts of +0.37 foundation factors for propAMMs and −0.22 for public AMMs. A markout compares a fill with a later reference worth, and a constructive quantity favors the maker.
Quiet-flow execution asks how a lot a dealer provides up in opposition to a comparatively secure reference. The proxy requires lower than 1 foundation level of reference motion from 5 seconds earlier than to at least one second after a fill.
Maker markouts ask what occurs to a commerce’s worth after the pool accepts it. Mixing the measures would flip proof about pricing and antagonistic choice right into a profitability declare the numbers can’t assist.
When an out of doors market strikes first, a pool nonetheless providing an previous worth can promote too cheaply or purchase too dearly. An arbitrageur brings the costs again into line, however the correction comes by way of a commerce in opposition to the liquidity already sitting within the pool.
Loss-versus-rebalancing research treats that arbitrage price as one element of LP economics. Returns additionally mirror asset publicity and costs earned, so an funding evaluation wants a place, a holding interval, and the revenue and prices attributable to it.
Buying and selling charges must be allotted accurately, whereas stock modifications, hedging, working bills and transaction prices additionally matter when relevant. The quick horizon leaves that accounting unresolved, and venue averages can’t set up that skilled swimming pools brought on mixture passive-LP losses.
Depositors want a return evaluation that features this wider steadiness sheet, and swappers can profit from liquidity whose operator actively manages pricing threat.
Leap Crypto’s April account describes propAMMs, together with its personal BisonFi, adapting prices and available liquidity to inventory, quote freshness, and the standard of incoming movement. Leap is an operator, and implementations differ.
A maker holding an excessive amount of of an asset can discourage trades that add extra of it, whereas a stale worth can justify withdrawing depth or widening a price. A routing path related to antagonistic choice can obtain totally different phrases from movement the maker considers much less dangerous.
Economically, these controls can enable a maker to cite extra tightly when it expects much less threat. Requiring each counterparty to obtain equivalent phrases would take away a technique of distinguishing that threat. The value an odd swapper in the end receives would nonetheless must be measured.
Jupiter’s AMM integration documentation exhibits {that a} devoted signer identifies trades originating at its frontend, describing that movement as retail and non-toxic. Nonetheless, figuring out origin is totally different from independently establishing that each commerce is innocent to the maker.
Non-public market-making logic can sit behind public settlement. The power to defend a worth might assist a agency provide cheaper liquidity, whereas entry to that worth is dependent upon the precise route and counterparty.
Quote reliability is a separate take a look at
For Tessera on Base, execution averaged 1.08 foundation factors worse by commerce and 0.56 by quantity than reconstructed previous-block-end quotes. Researchers name the block-timed price sample “spoofing.”
The researchers examine reconstructed pool output with execution, leaving particular person display screen quotes exterior the measure. The noticed sample supplies no direct proof of operator intent. Higher execution relative to a market reference and worse execution relative to an earlier quote can coexist.
In a March 20 report, routing supplier 0x described Base costs deteriorating between quote choice and settlement by way of block timing and unfold modifications. Its operators had been unnamed, in order that report can’t determine Tessera as the topic. 0x additionally said a coverage of reducing off sources till execution points are remedied.
If an marketed output attracts the order however a unique output is delivered, competitors on the marketed quantity can reward the incorrect venue. The query turns into whether or not routers examine what a dealer can obtain underneath the situations of that transaction.
Leap argued that routers deciding on executable costs when transactions run can largely shut the display-to-fill hole. The helpful design implication is {that a} maker may retain stock, freshness, and counterparty protections, offered the router compares outputs that already embrace them.
Jupiter’s current Swap API overview describes competitors between routing engines and a mechanism that sidelines underperforming sources. Its integration information additionally requires quote/execution parity exams in opposition to the identical pool snapshot.
A parity test measures settlement on one snapshot, however persistence by way of later updates is a separate query. Competitors between engines additionally leaves open whether or not every venue is reconsidered inside an executing transaction.
Evaluating executable output affords a design path, however its effectiveness would must be measured.
For a significant comparability, the executable output should mirror the identical commerce dimension, caller, present pool state, and relevant expenses. In any other case, a worth accessible to at least one routing path will be mistaken for a worth accessible to a different.
Jupiter paperwork a platform swap price on its Meta-Aggregator path and none on its Router path, whereas integrator charges and touchdown preparations can differ. A protocol-level unfold can’t stand in for the quantity in the end acquired in spite of everything relevant expenses.
The following helpful proof would examine quoted and delivered output on matched transactions, clarify which prices are included, and present how routing treats persistently underperforming sources.
For passive liquidity, a separate position-level return evaluation is required. Higher routing can enhance the swapper’s resolution whereas leaving the depositor’s funding query open.