Walmart, Microsoft and JPMorgan block NYSE-backed venture from tokenizing their shares
Walmart and 37 different corporations have objected to third-party tokenized variations of their shares buying and selling on OKXICE, the proposed round the clock inventory tokens venue backed by the proprietor of the New York Inventory Trade.
The objections present {that a} venue can earn buying and selling charges whereas issuers weigh pricing dangers and a restricted window to object.
The venue’s Oct. 28 notice lists Walmart alongside Microsoft, Alphabet and JPMorgan amongst 38 objectors.
OKXICE is owned equally by an Intercontinental Trade subsidiary and OKC USA. ICE operates the NYSE, however OKXICE is a separate venue proposing secondary buying and selling by means of automated liquidity swimming pools on the XLayer blockchain.
Beneath the SEC framework, the tokens should carry shareholder rights equal to traditional shares.
Oct. 24 stories listed 16 objectors, and the bigger roster now sharpens the issuer-participation drawback.
The charges go to the buying and selling enterprise
OKXICE’s service charge goes to the venue, whereas separate pool charges accrue to the buyers who provide property for buying and selling, whereas community charges go to the blockchain.
The SEC’s Sept. 17 exemption prohibits main issuance and preliminary choices on coated tokenized securities venues.
An issuer may nonetheless worth wider entry to its shares, however that potential profit differs from a direct cost or capital increase, and the charge schedule doesn’t quantify an issuer payoff.
Extra buying and selling can create a transparent income alternative for the venue with out giving the underlying firm an equally clear industrial incentive to take part.
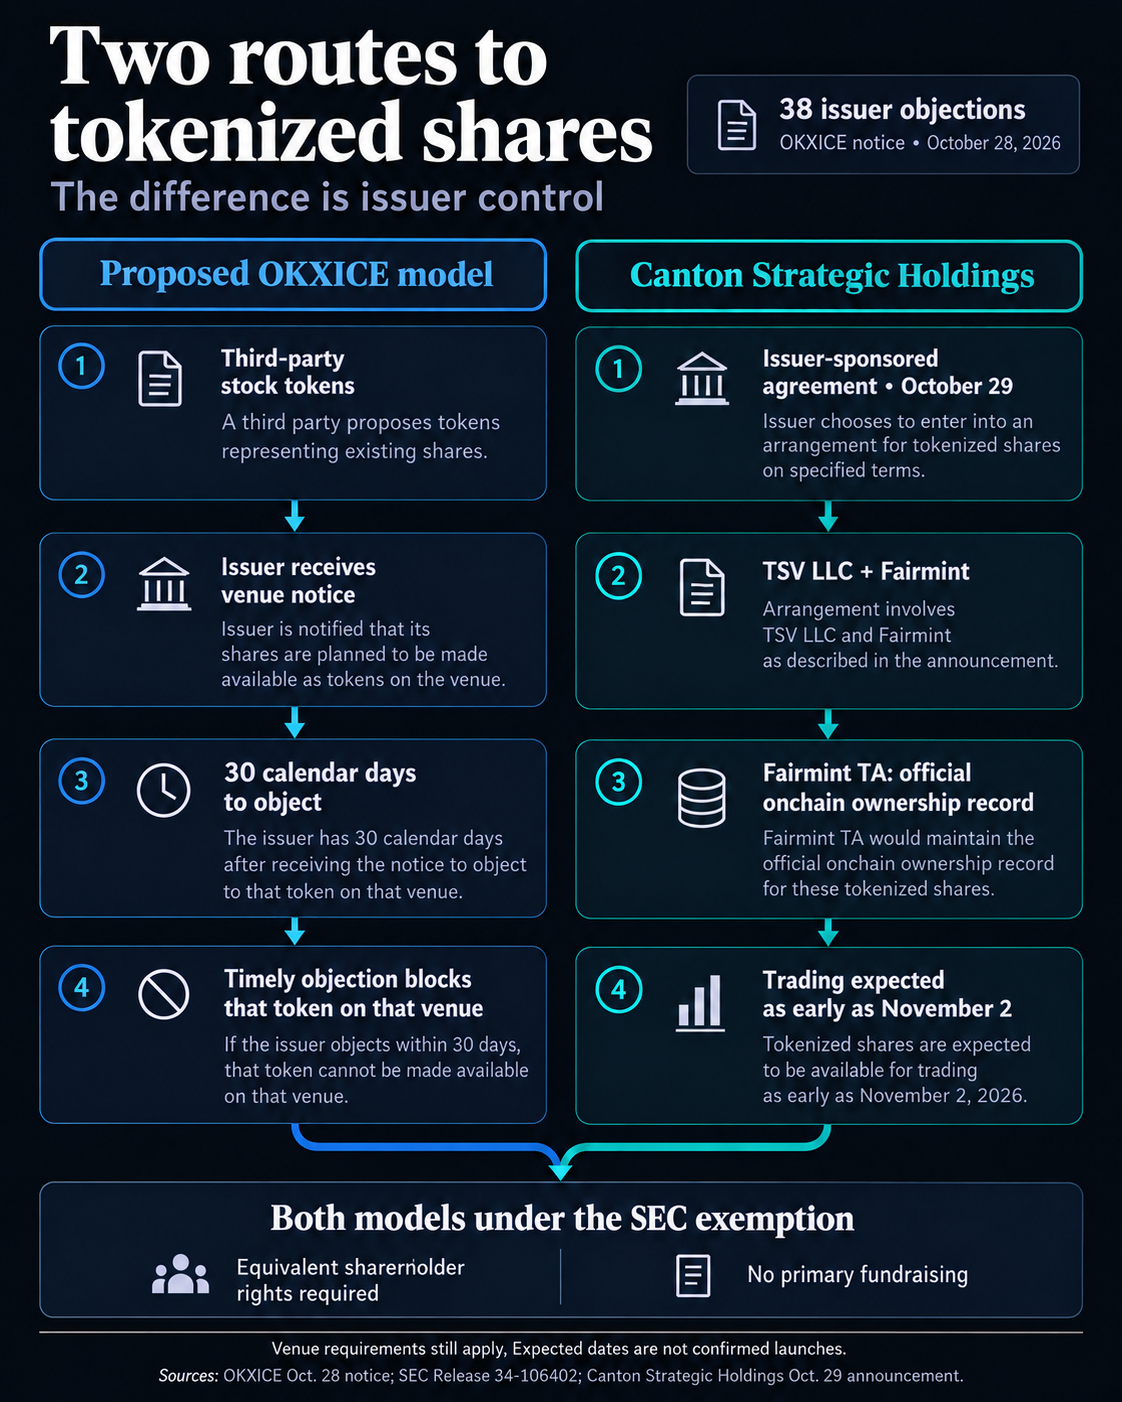
Earlier than providing a inventory tokenized by an unaffiliated third social gathering, a venue should notify the issuer. A written objection delivered by the thirtieth calendar day after the corporate receives that discover prevents the token from buying and selling on that exact venue.
SEC staff guidance additionally distinguishes this issuer course of from the separate public-notice interval earlier than a venue begins operations.
Part II.D of the order specifies no comparable routine issuer veto after the objection window, creating an incentive to refuse early whereas assessing a venue’s dangers and advantages.
On Oct. 19, the Securities Industry and Financial Markets Association proposed changes that would embrace affirmative issuer consent, an extended objection interval, and a common issuer opt-out.
A well-known share can have an unfamiliar worth
The SEC identifies shareholder-register upkeep and doable worth dislocation, together with hostile results on underlying inventory costs, as dangers issuers might weigh.
OKXICE’s proposed swimming pools worth transactions from their asset balances somewhat than a traditional order guide. The venue warns that token prices may diverge from underlying share costs, significantly when common inventory markets are closed, or pool liquidity is skinny.
A separate worth for a token representing an organization’s shares can create confusion about what the inventory is price.
OKXICE supplies for buying and selling stoppages, together with these tied to underlying-stock halts. Past its disclosed stoppages, it applies no further reference-price bands, so round the clock availability would not assure a dealer should buy close to the standard share quote.
Canton Strategic Holdings’ Oct. 29 announcement exhibits that the corporate agreed with tokenized securities venue TSV LLC to make its shares out there by means of an issuer-sponsored association and engaged Fairmint to tokenize them.
Fairmint TA would concern the tokens and preserve the official on-chain possession report, with buying and selling anticipated as early as Nov. 2.
Each sponsored and third-party tokens below the SEC framework should present equal shareholder rights. Canton’s distinction is that the corporate selected its intermediaries and ownership-record association.
The 38 objections depart OKXICE with an issuer-participation problem alongside its expertise plans. The sensible check is whether or not broader entry can supply corporations sufficient worth to simply accept the pricing and recordkeeping trade-offs, or whether or not venues will want extra preparations constructed with issuers from the outset.